 All posts
Itemized List for Insurance Claim Template Excel: A Step-by-Step Guide
Learn how to format an itemized list for an insurance claim in Excel. Discover the 12 mandatory columns, formatting rules, and how to avoid rejected claims.
Corey Everett built Arclyst from a background in Library and Information Science, with the goal of bringing structured information management into everyday home life.
Gemini-assisted drafts are reviewed by Corey Everett before publication.
Publisher: EverCreate Studio
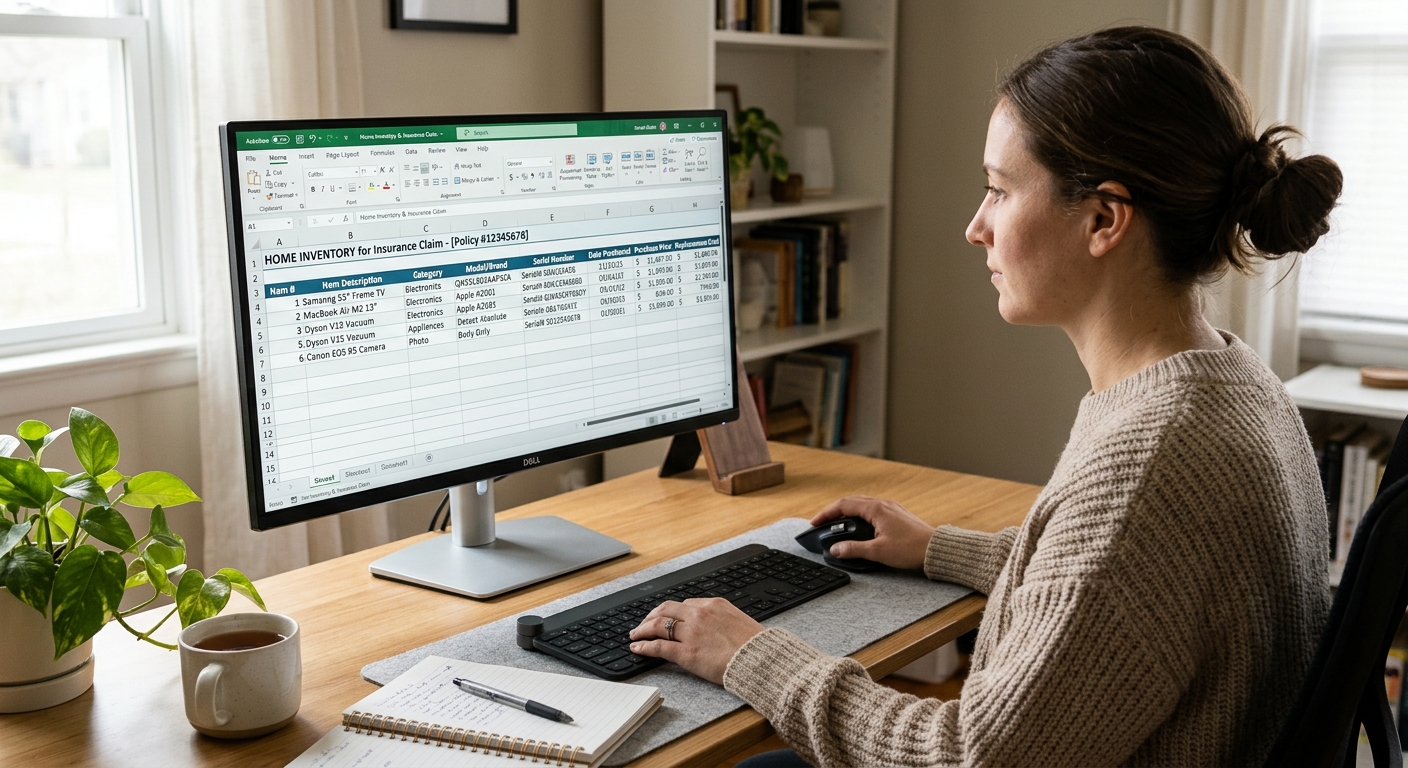
An itemized list for an insurance claim template in Excel is a structured spreadsheet containing one row per belonging and fixed columns for item name, room, purchase date, price, and serial number. It is formatted specifically so an insurance adjuster can verify proof of ownership and calculate replacement costs line by line.
Below is the exact column schema, data types, and sorting rules required to recreate an adjuster-ready template in Excel.
Key takeaways
- Use 12 fixed columns: An adjuster-ready claim list requires Item #, Room, Item Name, Brand, Model, Serial Number, Purchase Date, Purchase Price, Quantity, Condition, Estimated Replacement Cost, and Receipt/Photo Link.
- Never merge cells: Keep exactly one row per item. Merged cells break sorting, filtering, and the ability for adjusters to import the file into their carrier tools.
- Lock down data types: Format serial numbers as text, dates as real date values (YYYY-MM-DD), and prices as plain currency numbers so nothing gets misread or dropped by Excel.
- Organize by a single column: Use a "Room" column to organize items rather than creating separate worksheet tabs for every room, ensuring sorting and totals stay in one place.
- Link, don't embed: Link to photos and receipts stored in a cloud folder (like Google Drive) instead of embedding images directly, which bloats the workbook and causes crashes.
What is an itemized list for an insurance claim?
An itemized list for an insurance claim is a line-by-line record of damaged, stolen, or destroyed belongings, detailing each item's description, age, and estimated cost to replace. After a fire, burglary, or severe storm, your insurance carrier will ask for this document as proof of ownership before paying a contents claim.
A general statement like "about $20,000 of electronics and furniture in the living room" invites a lowball settlement because it gives the carrier nothing tangible to verify. Per-item detail is what adjusters actually price against.
The Insurance Information Institute recommends documenting belongings room by room, including photos and receipts where you have them. Building that record in Excel works well if you follow strict formatting rules, but most people struggle to finish one manually. If you would rather start from visual evidence, understanding why a video walkthrough of an insurance claim is only the first step can help you transition a photo-based record into a claim-ready list.
What columns should an itemized list for an insurance claim include?
An adjuster-ready itemized list needs 12 core columns in a fixed order. Keeping this order consistent across every row ensures the claim reads clearly and can be processed without unnecessary back-and-forth.
The 12 mandatory columns
| Column | Data Type | Notes |
|---|---|---|
| Item # | Number | Sequential ID (1, 2, 3...). Ensures one row per item. |
| Room | Text | Use a fixed set of names: Kitchen, Bedroom 1, Living Room, etc. |
| Item Name | Text | Be specific: "Sony WH-1000XM5", not just "headphones". |
| Brand | Text | Leave blank only if genuinely unknown. |
| Model | Text | Model number is highly preferred over a generic description. |
| Serial Number | Text | Format as text so Excel retains leading zeros (e.g., 00456). |
| Purchase Date | Date | Use a real date format (YYYY-MM-DD), not "a few years ago". |
| Purchase Price | Currency | Two decimals, plain numbers. No text like "about 50". |
| Quantity | Number | One row per item type, not per unit. |
| Condition | Text | Standardize terms: New, Good, Fair, Worn. |
| Estimated Replacement Cost | Currency | Current retail price for a similar item, not what you originally paid. |
| Receipt/Photo Link | URL | Paste a clickable Google Drive, Dropbox, or iCloud link. |
Columns for high-value items
For anything over roughly $500—such as fine jewelry, musical instruments, camera bodies, or specialized sporting equipment—you should add three additional columns to your template: Appraisal Date, Appraiser Name, and Document Link.
These three columns are often what separate a claim that gets heavily scrutinized from one that clears quickly. High-value items typically require scheduled personal property coverage (a rider), and adjusters will look for these specific fields. The full walkthrough of how these columns feed an actual claim lives in our insurance claim guide.
How do you format an Excel claim list so adjusters accept it?
Adjusters process claims line by line, often importing your Excel or CSV file directly into their own estimating software (like XactContents). If your formatting breaks their import tool, your claim gets delayed.
The "one row per item" rule
The golden rule of an insurance claim template is one row per item, one item per row. Never merge cells to group items together. Never combine two distinct items into a single line (e.g., typing "TV and soundbar, $900"). If you have a TV and a soundbar, they require two separate rows with their own respective brands, models, and prices. Merged cells break sorting, filtering, and automated imports.
Setting strict data types
Format the columns so nothing gets misread by the software:
- Dates: Enter dates as
YYYY-MM-DDor a consistent US format (MM/DD/YYYY). Never type text like "a few years ago" or "Spring 2021." If you only know the year, type01/01/YYYYand add a note in a separate column. - Currency: Currency cells must hold plain numbers formatted with Excel's built-in Accounting or Currency cell style. Do not manually type a "
500.00 is correct; ~500 is incorrect.
004928 into 4928), which technically falsifies the serial number.Workbook structure
Freeze the header row (View > Freeze Panes > Freeze Top Row) so your column titles stay visible while you scroll through several hundred lines.
Keep one sheet per property if you are documenting more than one home. Do not create a separate tab for every room in the house. A single sheet with a "Room" column allows the adjuster to sort, filter, and sum up the total claim value instantly.
Excel's built-in date and currency formats handle most of this if you apply them to whole columns instead of typing values by hand. Items people most often forget to document are worth a separate pass before you call the list done, as covered in what renters forget to document before an insurance claim.
If you would rather skip the spreadsheet entirely, Arclyst builds the same structured record from photos, room by room, and keeps it searchable. The Excel route works perfectly well; it just typically fails for most people at the ongoing update step, not the initial setup step.
What item details are mandatory versus optional on a claim inventory?
Not every cell in your spreadsheet needs to be filled for every single item, but leaving the wrong cells blank can stall your settlement.
Mandatory fields: Item name, room, estimated purchase price, age (or purchase year), and quantity. Adjusters use these five data points to calculate depreciation and price every line on your claim. A row missing any of these will likely be flagged. Furthermore, serial numbers and model numbers are mandatory for electronics, appliances, and anything valued over a few hundred dollars.
Optional but valuable fields: Brand, receipts, warranty dates, condition notes, and photos. If you only have time for the mandatory five, a photo of the item in its room substitutes for most of the optional fields as proof of ownership. We explain how a single image can carry a real claim in our guide on what actually counts as proof.
Honest limitation: Photos do not capture purchase price or age, so you still need to type those two columns into your Excel template yourself to calculate actual cash value vs replacement cost.
How do you organize an itemized claim list by room or category?
Organize your spreadsheet by room. Adjusters walk your claim the way you walk your house. A room-by-room sheet lets them match your list to damage photos, police reports, and floor plans without guesswork. It also exposes gaps in your own memory: an empty "Bedroom 2" section is a prompt to keep documenting, not a failure.
Category grouping (e.g., listing all electronics together, regardless of room) works better for only a few specific cases: collections stored across multiple rooms, specialized gear you move often, or a home office where equipment values dominate the entire claim. The same structure applies either way—just swap the grouping column.
If your list leans heavily toward professional equipment rather than standard home furnishings, the same room-first logic carries over to a small business equipment inventory.
How do you attach receipts and photos to an Excel claim inventory?
Do not embed images directly into the Excel workbook (using Insert > Picture). Inserted photos bloat the file size massively, slow down cloud syncing, and will almost certainly push you past email attachment limits when you try to send the list to your adjuster.
Instead, keep your photos and receipt scans in a dedicated cloud folder (like Google Drive, Dropbox, or OneDrive) named by room. Reference them from your spreadsheet using the Receipt/Photo Link column.
Using the HYPERLINK formula
To make the list user-friendly for the adjuster, use Excel's HYPERLINK formula to point each row at its file URL so they can click straight through.
The syntax is: =HYPERLINK("URL", "Link Text")
For example: =HYPERLINK("https://drive.google.com/file/d/12345...", "View TV Receipt")
Documentation quality directly affects how smoothly a claim moves. Delayed or incomplete proof of ownership is a common reason claims stall. Arclyst handles this differently: photos are the starting point, and each item's record carries its own images securely, so the linking is built-in rather than maintained by hand with formulas.
What mistakes cause itemized claim lists to be rejected or underpaid?
Even with a perfect Excel template, the data you put into it determines your payout. Avoid these common pitfalls:
Vague item descriptions
The most common rejection trigger is a vague item description. Typing "TV, $800" gives an adjuster nothing to verify. They will likely price it against the cheapest 32-inch television currently on the market.
Typing "Samsung 55-inch 4K Smart TV (UN55TU8000), serial 04X3-..." alongside a photo link and purchase date gives them exact data they can settle without a follow-up call.
Missing serial numbers
Missing serial numbers on electronics, appliances, and jewelry is the second-largest payout reducer. Without a serial number, carriers often classify items as unverified and pay generic contents rates instead of the specific item's true value.
Formatting and calculation errors
Other errors that slow claims include:
- Prices without dates (making depreciation impossible to calculate).
- Duplicate rows from copying and pasting between rooms.
- Receipts stored as loose email attachments with no clear link in the spreadsheet.
- Manual totals at the bottom of the sheet that don't match the actual sum of the line items (always use the
=SUM()formula).
Photos fix most of this ambiguity. A photo per item, even a quick phone shot, is the evidence adjusters trust most. Tools like Arclyst build the record from photos first, so the spreadsheet inherits proof instead of chasing it.
How do you turn an existing inventory spreadsheet into a claim-ready itemized list?
If you already have a basic home inventory spreadsheet, you don't need to start over. You just need to map your existing columns onto the claim schema one row at a time.
- Rename headers to the adjuster's vocabulary: Change "What it is" to "Item Name," change "Cost" to "Estimated Replacement Cost," and change "Bought" to "Purchase Date."
- Clean up unmapped columns: Anything that does not map to the 12 core columns, like a "Store Location" column, should be moved into a general "Notes" column at the far right of the sheet.
- Fix data types: Ensure dates are real Excel dates and prices are formatted as currency.
- Fill the gaps: Blank cells read as missing proof of ownership. If you don't know a purchase date, estimate the year. If you don't know the brand, type "Unknown" rather than leaving it blank.
If your current spreadsheet is mostly a mess of embedded photos and half-finished rows, retrofitting it might take longer than starting fresh. Tools built around photo-first entries can be faster than fixing a sparse spreadsheet. Arclyst works exactly this way: you start from room-by-room photos, and the system helps build the searchable catalog with the exact fields your claim list needs.
Should you build the spreadsheet yourself or start from photos?
Manual Excel entry gives you the absolute most control over columns, formulas, and formatting. However, it fails for the exact same reason most home inventories fail: it depends on you sitting down and typing item after item into a blank sheet for hours on end.
Photo-first capture flips the order. You take pictures room by room, then build the itemized list from what the photos actually show.
That is where Arclyst fits in. It helps turn your home photos into a searchable catalog with serial numbers, receipts, and warranties attached, so proof of ownership exists before you ever open Excel.
The honest tradeoff: AI and photo-first capture can occasionally misread details, meaning you still need to review the data and export it into the spreadsheet structure adjusters expect. If you already keep receipts and serial numbers highly organized in folders, manual entry may suit you perfectly fine. But if you have tried and failed to finish a spreadsheet in the past, start with photos.
FAQ
How many items should I list on an insurance claim inventory?
List every damaged, stolen, or destroyed item individually, one row each. A typical furnished home runs several hundred lines, so work room by room rather than estimating a total. Grouping "kitchen items, $3,000" as one line invites a lowball settlement, because adjusters price each verified row. Anything over roughly $500 deserves its own dedicated entry with a serial number and photo.
Do I need receipts for everything on an itemized claim list?
No. Receipts help most on high-value items like electronics, jewelry, and appliances, where a serial number plus proof of purchase speeds settlement. For everyday belongings, a photo of the item in its room substitutes for most optional fields as proof of ownership. If a receipt is missing, record the purchase year and estimated price anyway; typing "unknown" or providing an honest estimate beats leaving a blank cell.
Can I use Google Sheets instead of Excel for my insurance claim template?
Yes. The column schema, one-row-per-item rule, and formatting rules carry over directly to Google Sheets. Sheets actually adds two advantages: HYPERLINK formulas point each row at photos or receipts stored seamlessly in Google Drive, and the file syncs automatically to the cloud, ensuring your list survives a laptop loss. Just remember to export it to an .xlsx file (File > Download > Microsoft Excel) before submitting if your adjuster requests an Excel file specifically.
What do I do if I already lost everything and never made a list?
Rebuild from the evidence that survives. Look for bank and credit card statements showing purchases, online order histories from Amazon or other retailers, email receipts, and your phone's photo library. Appraisals or insurance riders are crucial for jewelry. List what you can verify first, estimate the rest honestly, and mark uncertain fields as such. Carriers expect post-loss inventories to be reconstructed; documented estimates still beat a single lump-sum guess.