 All posts
Small business equipment inventory for insurance and taxes
A small business equipment inventory tracks fixed assets like laptops and tools for insurance claims and tax depreciation. Learn how to document your gear.
Corey Everett built Arclyst from a background in Library and Information Science, with the goal of bringing structured information management into everyday home life.
Gemini-assisted drafts are reviewed by Corey Everett before publication.
Publisher: EverCreate Studio
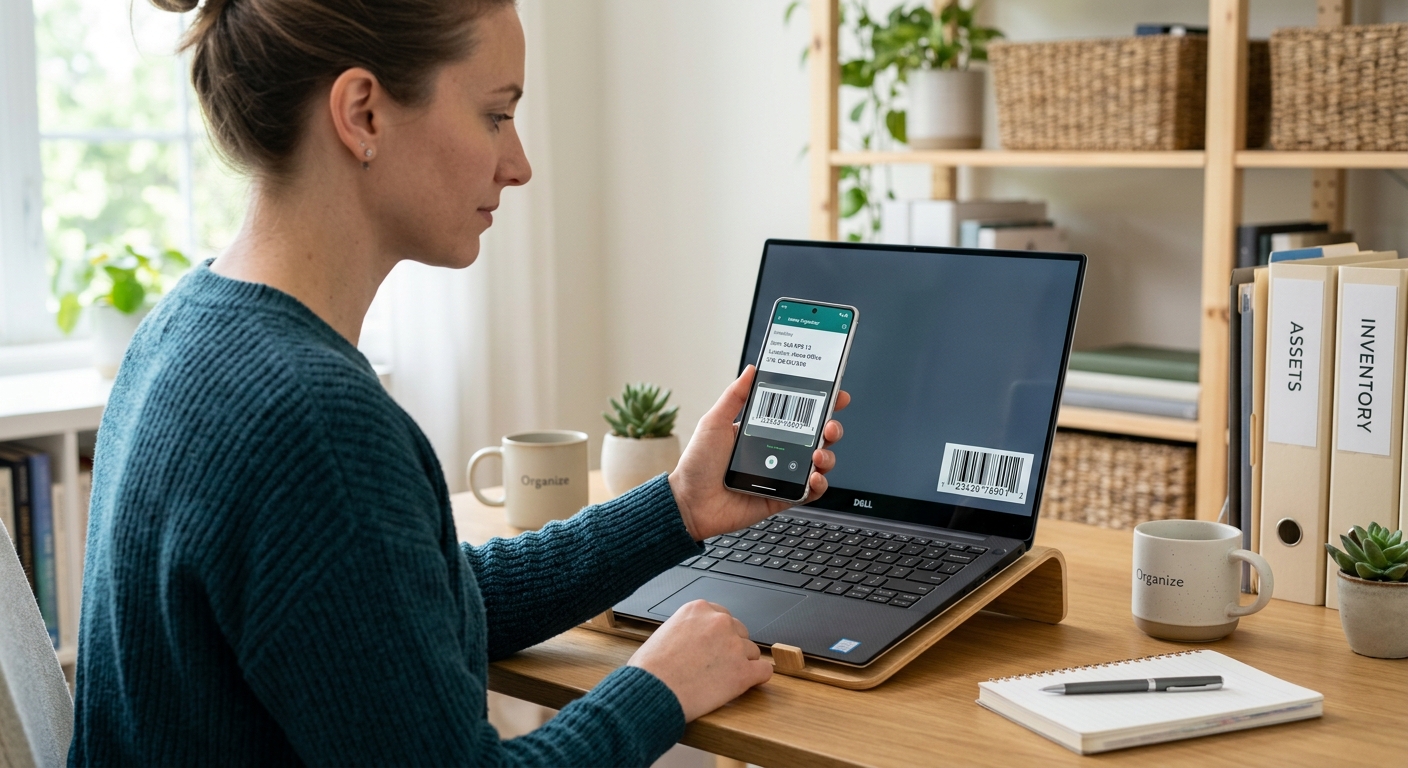
A small business equipment inventory is a documented list of the physical assets used to run your company. When a pipe bursts over your office or a work van is broken into, a spreadsheet from three years ago will not satisfy an insurance adjuster. You need current, verifiable proof of ownership to replace your gear and resume operations.
Business asset tracking goes beyond disaster recovery. It provides the exact purchase dates and prices your accountant needs for tax depreciation. It also creates a clear paper trail for employee onboarding and offboarding, ensuring company-issued laptops and phones are returned. This guide explains how to document your business assets, what details to capture, and why an equipment inventory app is safer than a manual spreadsheet.
TL;DR
- Understand the difference between retail inventory (goods you sell) and fixed assets (equipment you use to run the business).
- Capture serial numbers, purchase dates, receipts, and photos for every major asset over a specific dollar threshold.
- Maintain accurate records to support commercial property insurance claims and calculate tax depreciation schedules.
- Track company-issued hardware assigned to remote employees to prevent asset loss during turnover.
- Use an equipment inventory app to digitize records rather than relying on easily lost paper receipts or manual spreadsheets.
Fixed Assets vs. Inventory: What Are You Tracking?
Business owners often use the word "inventory" to mean two different things. Mixing them up leads to accounting errors and inadequate insurance coverage.
Retail inventory refers to the stock you intend to sell to customers. If you run a coffee shop, your retail inventory includes coffee beans, milk, and paper cups. These items turn over quickly and are tracked through your point-of-sale system.
Equipment inventory refers to your fixed assets. These are the items you retain to operate the business. In that same coffee shop, fixed assets include the $12,000 espresso machine, the commercial refrigerators, the POS terminals, and the lobby furniture.
This guide focuses entirely on tracking fixed assets. Here is how that distinction looks across different industries:
| Industry | Retail Inventory (Goods to Sell) | Fixed Assets (Equipment to Track) |
|---|---|---|
| Coffee Shop | Beans, milk, syrups, paper cups | Espresso machines, grinders, POS terminals |
| Construction | Lumber, nails, concrete, drywall | $3,500 laser levels, excavators, work trucks |
| IT Agency | N/A (Service-based business) | MacBook Pros, server racks, office furniture |
| Landscaping | Mulch, fertilizer, replacement plants | Commercial zero-turn mowers, leaf blowers, trailers |
The Financial Case for Business Asset Tracking
Documenting your equipment requires an upfront time investment. However, it protects your business against specific financial risks: underpaid insurance claims, inaccurate tax filings, and lost hardware.
Insurance Claims and Proof of Ownership
Commercial property insurance policies require you to prove you owned an item before they will pay to replace it. If a fire destroys your design studio, the insurer will ask for a detailed schedule of lost items.
Claiming "five laptops and a server" is not enough. Adjusters expect the make, model, purchase date, and replacement cost for each item. Without receipts or photographic evidence, an insurer may default to a lower actual cash value payout. This leaves you without enough capital to buy replacement gear. Proper documentation speeds up the insurance claim process and helps ensure a fair settlement.
Tax Preparation and Depreciation
When you purchase expensive equipment, you often deduct the cost from your business taxes over several years through depreciation. Alternatively, you might take a Section 179 deduction to write off the full purchase price in the first year.
Both methods require strict record-keeping. The IRS expects you to know exactly when an asset was placed into service, what it cost, and when it was retired or sold. Always consult a certified tax professional regarding your specific deduction strategy. Recognize that your accountant relies entirely on your equipment log to calculate those figures accurately.
Employee Accountability and Turnover
Remote and hybrid work models mean company assets are scattered across multiple zip codes. When an employee resigns, you need a definitive list of the hardware they must return.
Without a centralized log, a $1,200 laptop or a $400 monitor can easily slip through the cracks during offboarding. Assigning assets to specific employees in your inventory system creates accountability. It also prevents you from accidentally purchasing duplicate equipment when you already have unused hardware sitting in a closet.
Maintenance and Warranty Tracking
Heavy machinery, specialized tools, and enterprise tech require regular maintenance. A broken $5,000 commercial oven halts your bakery's production entirely.
An equipment inventory allows you to track warranty expiration dates and scheduled service intervals. If a hard drive fails or a power tool motor burns out, you can instantly check if the item is still under the manufacturer's warranty before paying out of pocket for a replacement.
What to Include in Your Equipment Log
Your tracking requirements scale with the complexity of your business. A freelance videographer needs to track serial numbers on lenses and camera bodies. A construction firm needs to track heavy machinery and power tools assigned to different trucks.
Set a minimum value threshold for your inventory. Many small businesses only track items worth more than $300 or $500. Tracking every $10 stapler wastes time. For items above your threshold, capture the following data points:
- Item Name: Provide a clear, specific description (e.g., "Herman Miller Aeron Chair" instead of "Office Chair").
- Make and Model: Critical for establishing replacement cost during an insurance claim.
- Serial Number: The definitive identifier for electronics, machinery, and tools. This is also required for filing police reports after a theft.
- Purchase Date: Required for tax depreciation schedules and warranty claims.
- Purchase Price: The exact amount paid, excluding sales tax if applicable.
- Current Condition: Note any existing damage, such as a cracked screen or a dented casing.
- Location or Assignment: Note which office room the item is in, which job site it is deployed to, or which employee currently holds it.
- Receipts and Warranties: Attach digital copies of the original invoice and warranty terms.
- Funding Source: Note if the item is owned outright, financed, or leased. Leased equipment often has specific insurance requirements.
How to Build Your Small Business Equipment Inventory
Building an asset log from scratch feels overwhelming. Break the process down into manageable steps to avoid disrupting your daily operations.
1. Define Your Tracking Categories
Before you start counting items, decide how you will categorize them. Common categories include IT Equipment, Office Furniture, Specialized Machinery, Vehicles, and Field Tools. Establishing these buckets early keeps your list organized as it grows.
2. Go Room by Room
Do not attempt to document the entire business from memory. Walk through the premises physically. Start with the IT closet, move to the main office floor, and finish in the breakroom. Documenting one room at a time ensures you do not miss hidden assets like network switches or backup generators.
3. Audit Remote and Field Assets
Your physical sweep will not capture everything. Send a standardized form to your remote employees asking them to confirm the company hardware in their possession. Require them to submit photos of the items and the serial number stickers. Do the same for foremen managing tools on active job sites.
4. Photograph the Data Plates
Typing out 16-character serial numbers leads to transcription errors. A single wrong digit can invalidate a warranty claim. Instead, take a clear photograph of the manufacturer's data plate or sticker on the back of the device. Keep this photo attached to the item's digital record.
5. Digitize Your Receipts
Paper receipts fade and get lost in filing cabinets. Thermal paper receipts from hardware stores often become entirely blank after a year. Scan your invoices immediately upon purchase. If you buy equipment online, export the order confirmation as a PDF and attach it to the asset record.
6. Establish an Update Protocol
An inventory is only useful if it is accurate. Create a standard operating procedure for new purchases. When a manager buys a new piece of equipment, they must log it into the inventory system before deploying it. Similarly, log items as "retired" or "sold" when you dispose of them.
Spreadsheets vs. Equipment Inventory Apps
Spreadsheets are the default choice for new businesses because they are free and familiar. However, they break down quickly as your company grows.
A spreadsheet cannot easily store high-resolution photos, PDF receipts, or warranty documents in a single, accessible view. Multiple employees editing a shared spreadsheet often leads to accidental deletions or version control issues. Furthermore, scrolling through hundreds of rows on a mobile phone while standing in a supply closet is frustrating.
Dedicated equipment inventory apps solve these problems. When searching for software, look for tools that prioritize speed of entry, photo attachments, and secure export options.
Arclyst is designed to solve the exact problem of asset documentation. Instead of typing out every detail, you can photograph your office equipment. Arclyst uses AI to help identify, describe, and categorize the items by room or employee. You can attach receipts, log serial numbers, and generate a PDF Claim Pack if you ever need to file an insurance claim.
Arclyst also offers QR sharing on paid tiers, allowing you to generate codes to stick on your equipment for easy tracking. You can test the workflow directly via the interactive demo.
FAQ
How often should I update my business equipment inventory?
Update your records immediately whenever you purchase new equipment, sell an old asset, or assign hardware to a new employee. Conduct a full physical audit once a year to verify the list matches your actual holdings. Many businesses schedule this audit right before tax season.
Does commercial property insurance cover remote employee laptops?
Coverage depends entirely on your specific policy. Many standard commercial property policies only cover items located at the primary business address. You may need an "off-premises" endorsement or inland marine coverage to protect laptops and tools taken to job sites, coffee shops, or home offices.
What is the difference between a fixed asset and an expense?
Generally, an expense is a low-cost item consumed quickly, like printer paper, breakroom coffee, or shipping tape. A fixed asset is a higher-value item with a useful life of more than one year, like the printer itself, a commercial refrigerator, or a delivery van.
How do I track serial numbers efficiently?
Stop typing them manually. Take clear, well-lit photos of the serial number stickers. If you use an inventory app, attach that photo directly to the item's digital profile so it is permanently linked to the asset. This prevents typos and provides visual proof for insurers.
What if I lost the original receipt for my business equipment?
If you purchased the item online, search your email for the order confirmation. If you bought it from a vendor with whom you have an account, ask them to reprint the invoice. If no receipt exists, take clear photos of the item, note the serial number, and find a current online listing for the exact make and model to establish its replacement value.
Should I include software and digital assets in this inventory?
Physical equipment inventories generally exclude software licenses, domain names, and digital subscriptions. However, if you purchase a physical server that includes proprietary software required to run it, you should note that software in the server's asset profile. Track standalone digital assets in a separate IT management spreadsheet.
Secure Your Business Assets with Arclyst
Your equipment is the engine of your business. Do not wait for a theft, a fire, or a messy employee departure to realize your asset records are incomplete. Documenting your gear ensures you can file accurate insurance claims, maximize your tax deductions, and keep your operations running smoothly.
Arclyst helps you catalog your fixed assets quickly using photo-based AI identification. It keeps your receipts, serial numbers, and proof of ownership in one secure place. The free tier allows up to 55 items and 15 AI scans per day, making it easy to test. Start documenting your business equipment for free at arclyst.org.
Related guides
Want a frictionless way to catalog what you own? Try Arclyst — free for 55 items. Snap a photo, AI fills in the details.